What is a business credit score?
A business credit score is a number that shows how creditworthy your company is. It’s based on your financial history, including payment behaviour, outstanding debts, and public records. Lenders and suppliers use it to assess the risk of doing business with you and decide whether to offer credit or finance.
Your business credit score explained
Your business credit score helps lenders, suppliers and other businesses assess how financially reliable your company appears. Generally, the higher your score, the lower the risk your business is considered to present.
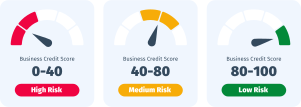
Business credit scores typically range from 0 to 100, although scoring systems and risk categories vary between credit reference agencies. Using Experian's scale as a guide, the ratings can be broadly understood as follows:
What is a high-risk business credit score?
A score of 0–40 indicates a high-risk business. Lenders and suppliers may consider your company more likely to experience difficulties meeting its financial commitments, which could make it harder to access credit or result in less favourable terms.
What is a medium-risk business credit score?
A score of 40–80 indicates a medium-risk business. Lenders and suppliers may look more closely at your company's financial circumstances, payment history and existing debts when deciding whether to offer credit.
What is a low-risk business credit score?
A score above 80 indicates a low-risk business. This suggests your company has a stronger credit profile, which may improve your chances of accessing finance and securing favourable terms. However, your credit score is only one factor lenders consider when assessing an application.
How to improve your business credit score
There are several steps you can take to help improve your business credit score. While improvements may take time, the following actions can help demonstrate that your business manages its finances responsibly.

1. Pay Bills on Time
Consistently paying your bills on time is one of the most effective ways to boost your credit score. It shows lenders and suppliers that you’re reliable and can manage debt responsibly.
2. Check Your Credit Report Regularly
Errors on your credit report can lower your score. Check your report frequently to spot mistakes or outdated information, and correct any inaccuracies as soon as possible.
💡 TIP
Want to check your company credit report? Read our guide on how to check your company credit report for free.
3. Avoid County Court Judgments (CCJs)
CCJs can severely damage your credit rating and remain on your record for six years. If you’re struggling with payments, speak to creditors early to avoid legal action.
💡 TIP
If you're seeking funding, check out our guide on securing a business loan with a CCJ that's packed with tips to help improve your chances of approval.
4. File Company Accounts on Time
Late filing of your annual accounts or confirmation statement with Companies House can signal poor financial management and may harm your company’s credit profile. Make sure to submit your accounts and returns on time to show that your business is well managed.
5. Limit Multiple Credit Applications
Before applying for business finance, compare your options and check the eligibility criteria. Multiple credit applications, particularly those involving hard credit searches, may affect your credit profile. Where available, use an eligibility checker that won't affect your credit score, such as our business loan comparison tool, to help you explore your options.
💡 TIP
Want to understand how credit checks work when applying for business finance? Read our guide: Is it possible to get a business loan with no credit check?
6. Keep Credit Utilisation Low
Using a large proportion of your available credit or carrying high levels of debt may indicate financial pressure. Keep track of your borrowing, make repayments on time and avoid taking on more credit than your business can comfortably afford.
7. Build a Positive Credit History
If your business has a limited credit history, paying suppliers within their agreed terms and managing existing business credit responsibly, such as making business loan repayments on time, can help establish a positive record.
8. Separate Personal and Business Finances
Keeping business and personal finances separate helps build a distinct credit history for your company. Opening a dedicated business bank account and using business credit responsibly can strengthen your business credit profile.
9. Reduce Outstanding Debt
High levels of outstanding debt can negatively affect your business credit score. Focus on gradually paying down what you owe to improve your credit rating and cash flow.
💡 TIP
Struggling with debt? Check out our guide on how to get free debt advice for your business.
10. Get Professional Help
If you're struggling to improve your business credit score, consider seeking advice from a financial advisor or credit specialist. They can provide tailored strategies to enhance your creditworthiness and help you navigate complex financial challenges.
Why your business credit score matters
Your business credit score isn’t just a number it’s a key factor in your company’s financial success. A stronger credit score can unlock valuable opportunities that help your business grow and thrive, including:
- Improve your chances of accessing business loans and other forms of credit
- Potentially secure more competitive interest rates and borrowing terms.
- Help negotiate favourable payment terms with suppliers
- Demonstrate financial credibility to prospective business partners
- Make it easier for other businesses to assess your company's creditworthiness
Improving your business credit score takes time, but small steps such as paying bills on time, managing debt responsibly and keeping company records up to date can strengthen your credit profile. Regularly checking your credit report can also help you identify areas for improvement and put your business in a stronger position when applying for finance or negotiating payment terms with suppliers.